
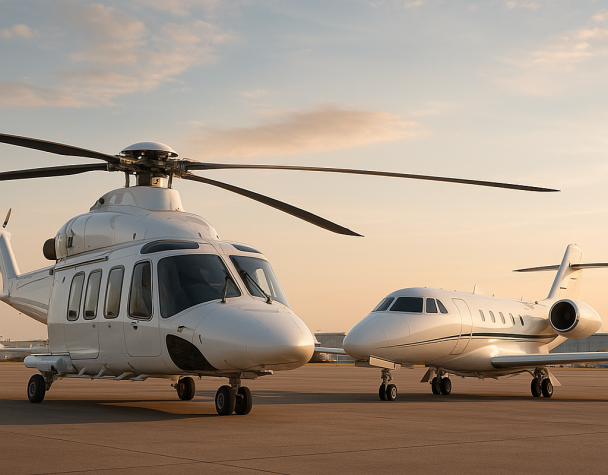
TransDigm’s Extant Aerospace Acquires $240 Million Rotorcraft and Business-Jet Portfolio
Fri, September 25, 2026TransDigm Group’s Extant Aerospace division has completed a material acquisition within the past week, purchasing a portfolio of rotorcraft, land systems and business-jet products for approximately $240 million in cash. This marks the latest in TransDigm’s strategic acquisition spree, following earlier deals such as the Prince & Izant acquisition and the aborted Stellant Systems transaction.
This deal was disclosed via a recent institutional filing, confirming the transaction details and purchase price. While TransDigm did not issue a press release, the filing reveals a clear expansion of its product portfolio across commercial and defense segments, notably in rotorcraft and business-jet areas previously targeted through its specialty parts emphasis.
Acquisition Expands Specialty Portfolio
The acquired assets include proprietary products serving high-cost-of-failure aerospace, defense and turbine applications. This addition reinforces TransDigm’s business model focused on niche components with strong aftermarket potential and limited competition. It builds on the July acquisition of Prince & Izant for roughly $1.066 billion, which added specialty metal and brazing products. Together, these deals underscore ongoing portfolio bolstering across diverse aerospace assets.
Strategic Momentum Amid M&A Activity
TransDigm’s recent M&A activity stands out in its sector. The firm withdrew from the $960 million Stellant Systems deal in July, following regulatory concerns, before pivoting to more manageable targets like Prince & Izant and now this $240 million rotorcraft and business-jet portfolio — a practical continuation of its acquisition strategy.
Outlook for TransDigm Shareholders
While TransDigm has not linked a share-price movement to the most recent acquisition, investors gain clarity on the company’s consistent capital allocation approach and its preference for high-margin, aftermarket components. The acquisition aligns with TransDigm’s value-creation strategy and could be viewed positively by investors focused on recurring revenue streams from critical aerospace subcomponents.
Investors tracking TransDigm stock (TDG) should consider this acquisition in the context of the company’s broader M&A momentum and its history of margin durability and aftermarket exposure. Continued integration of such assets could reinforce earnings resilience over time.
The cash acquisition of rotorcraft, land systems, and business-jet assets for $240 million by Extant Aerospace is a tangible, verifiable development this week, signaling TransDigm’s strategic focus on expanding its proprietary aftermarket portfolio.